The clearest signal out of South Florida industrial this week is institutional capital doubling down on Miami-Dade small-bay — and doing it with a deal structured in a way that says something specific about how these buyers see the asset class.
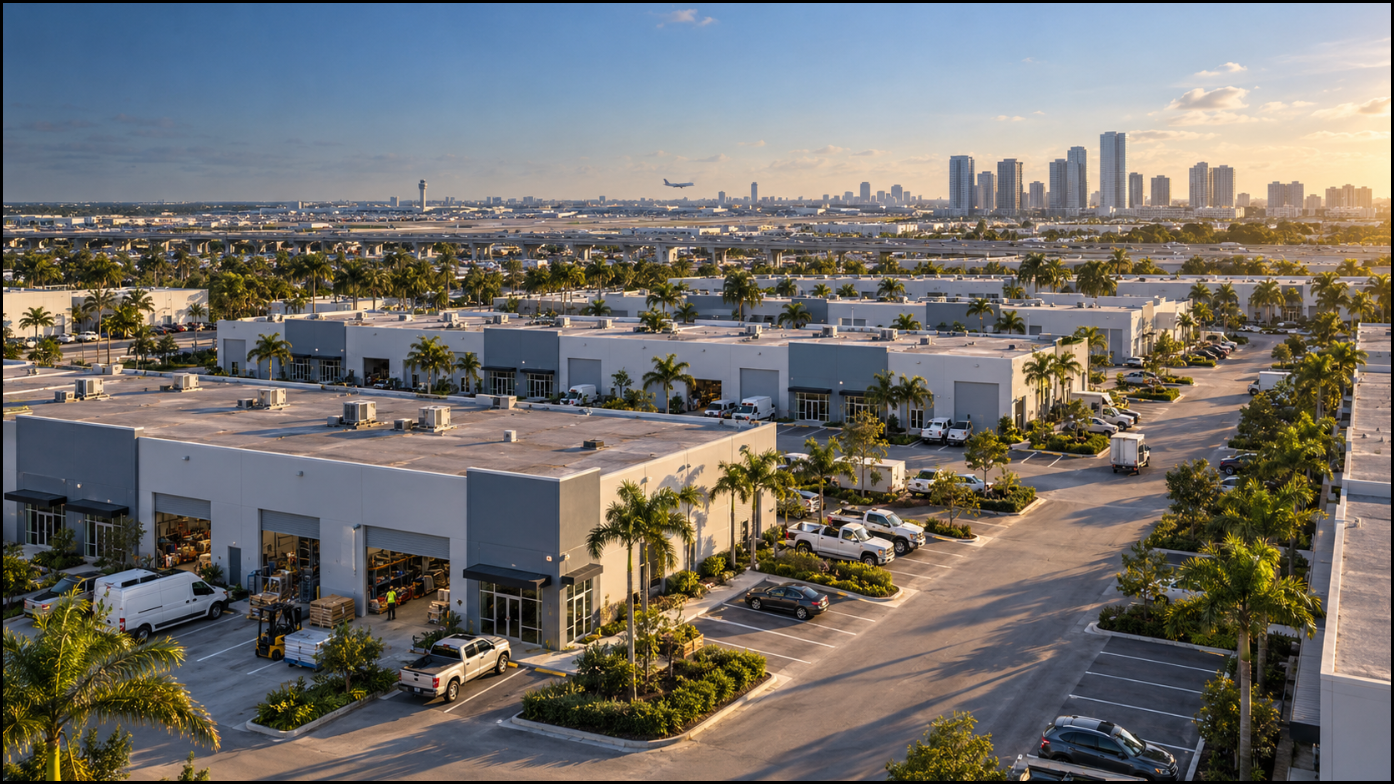
On September 9, Longpoint Partners acquired a 10-building, 729,901-SF industrial portfolio for $195 million, or roughly $267 per square foot. The portfolio is 90% occupied across 74 tenants, with average tenant size just under 10,000 SF, and buildings ranging from 17- to 25-foot clear with 231 loading positions.
Longpoint specifically cited limited new-supply potential and a diversified pool of smaller tenants as reasons for the acquisition — not a single credit anchor, not a new-vintage box, but exactly the kind of granular, hard-to-replicate infill product we have been flagging as a distinct market from commodity big-box space.
Paying $267/SF for a portfolio that is only 90% occupied is the more interesting detail here. It implies Longpoint is underwriting upside through lease-up, renewals and mark-to-market rents on the vacant and below-market space, rather than demanding full stabilization before deploying capital. That is a materially more aggressive posture than we’d expect on commodity big-box product at a similar vacancy level, and it is a vote of confidence in small-bay’s ability to re-lease quickly and reprice upward.
This trade also lands immediately behind the Ares/BGRE acquisitions we covered last week. Two large, well-capitalized buyers making conviction bets on modern and infill Miami-Dade industrial within the same two-week window is no longer a pattern we can dismiss as isolated deal flow.
Miami’s operating numbers are mixed but explain the appetite. Q2 produced 3.0 million SF of leasing and 782,677 SF of positive absorption, but 769,100 SF of deliveries pushed countywide vacancy to 7.7%, with asking rent at $17.19/SF NNN and another 2.9 million SF still under construction.
The number that actually matters for small-bay owners is different from the countywide figure. Colliers research has shown South Florida small-bay vacancy running around 2.3%–3.0%, versus roughly 8.5%–9.8% for large-box product. That gap is the entire thesis behind this week’s trade.
Don’t tell a 7,500-SF Doral owner that Miami industrial vacancy is 7.7% without qualifying it — their actual competitive set behaves like a market closer to 3% vacancy, not 7.7%. Institutional capital is now pricing that distinction explicitly, and owners of well-located small-bay product should be having a very different valuation conversation than owners of big-box space right now.
Market commentary based on reported transaction data and Colliers/CBRE research; not investment advice. Figures per public deal reporting for the week of September 14, 2026.
The most consequential signal out of Miami-Dade this week wasn't a leasing statistic — it was two separate trades that both said the same thing: institutional…
Jose Rueda · Sep 8, 2026Broward's fundamentals are improving, but tenants still have substantially more choice than they did two years ago — and this week's capital-markets activity shows exactly how…
Jose Rueda · Aug 26, 2026Talk to one of our agents about leasing, buying or selling industrial and commercial space in South Florida.