The market signal out of Miami-Dade this week isn’t a broad industrial rebound — it’s a bifurcation, with the strongest evidence of renewed tenant absorption concentrated specifically around aviation, MRO, manufacturing and airport/logistics uses.
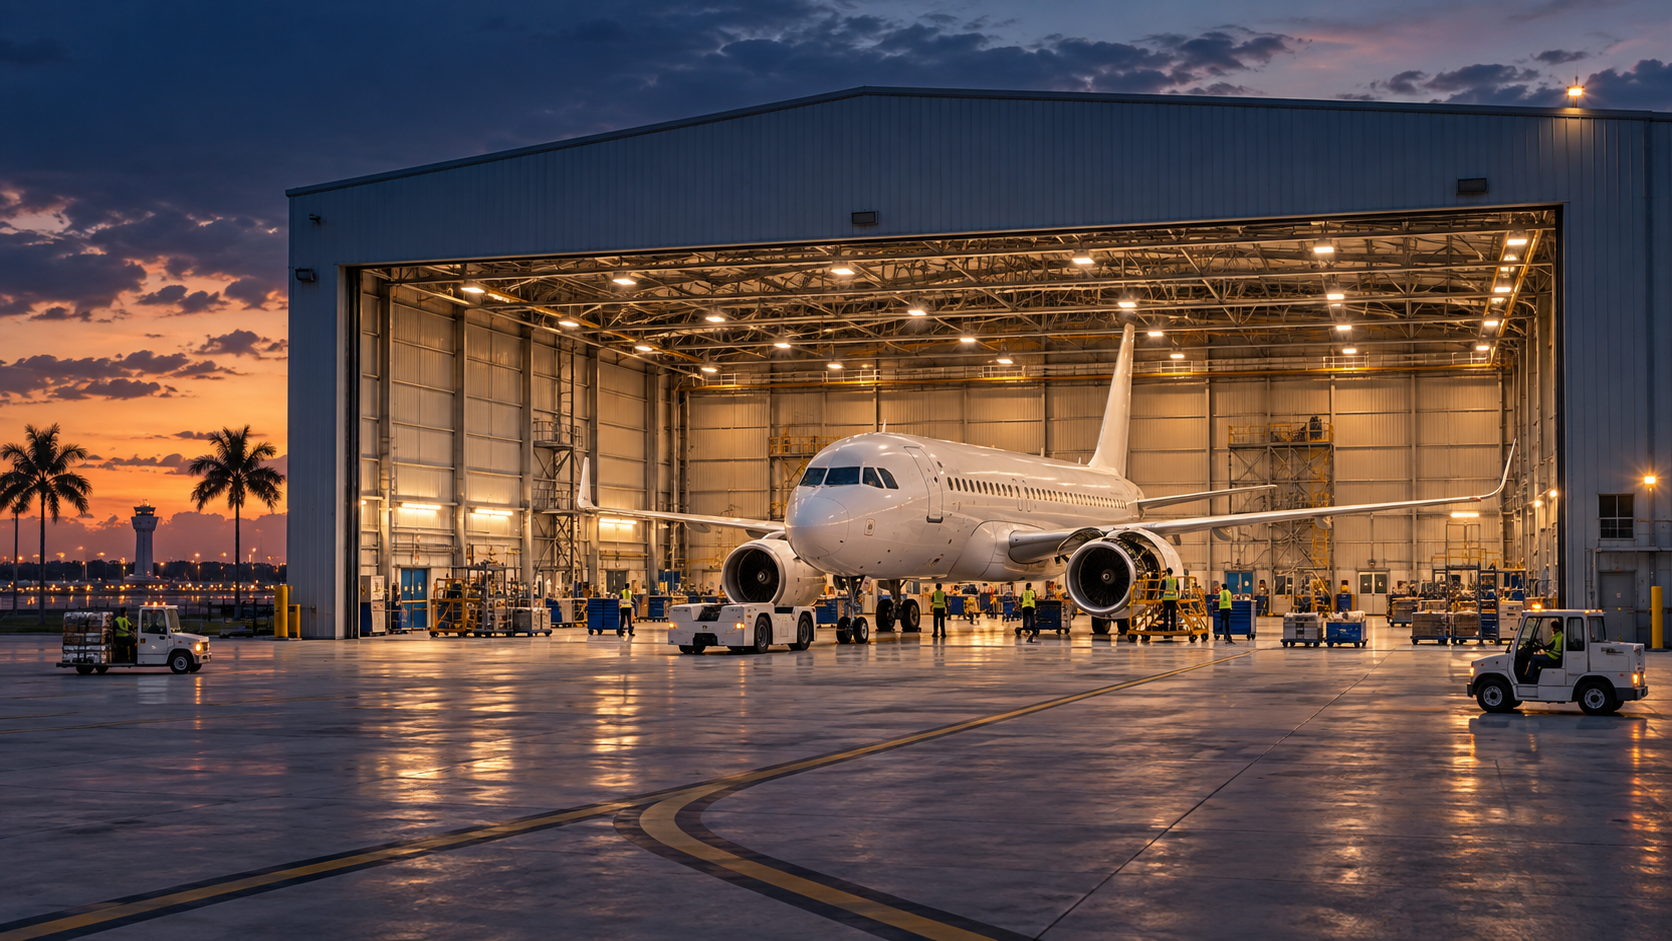
On August 17, AAR opened an additional 100,000+ SF at Miami International Airport for three heavy-maintenance lines, adding roughly 200 new full-time jobs. Critically, the space was built around a long-term airline maintenance requirement, not speculative demand — this is real, structural aviation growth, not a landlord betting on future absorption.
Powerhouse Engines reportedly signed a 10-year, 90,000-SF lease at Tamiami Logistics Center in West Kendall, nearly quadrupling its existing footprint — a strong signal of an established occupier scaling up, not a new market entrant testing demand.
And earlier this month, Vision Aerospace took 76,605 SF at Palmetto 74 Logistics Center in Medley, taking the 403,496-SF project from roughly 11% occupied last September to 100% leased in about ten months. That kind of lease-up velocity on a project that size is a meaningful data point on its own.
Three separate aviation/MRO-adjacent leases signing in close succession is more meaningful than any one generic warehouse deal, because it points to an expanding ecosystem rather than an isolated transaction. Aviation/MRO suppliers, precision manufacturers, aerospace parts distributors, and businesses servicing MIA should move near the top of the prospecting list right now — second-order demand from vendors and suppliers frequently follows the major operators into a market.
Q2 vacancy reached 7.7%, but that increase was largely supply-driven: 769,100 SF delivered while the market still absorbed roughly 783,000 SF. Leasing totaled about 3.0 million SF during the quarter, and asking rents reached $17.19/SF NNN, up 1.5% year over year, with another 2.9 million SF under construction. The vacancy tick-up is a supply story; the aviation/MRO cluster is the demand story, and the two shouldn’t be read as contradicting each other.
If you work with aviation-adjacent, MRO, or precision manufacturing tenants, Miami-Dade right now is a market where that specific demand is real and accelerating — not a general leasing environment where any tenant type is absorbing space equally. We’d prioritize prospecting in and around this cluster over generic warehouse-user outreach for the next several months.
Market commentary based on reported leasing activity and public deal reporting; not investment advice. Figures per market data for the week of August 24, 2026.
Talk to one of our agents about leasing, buying or selling industrial and commercial space in South Florida.